Offshore benchmarks have lagged while mainland hardware names have led. Capturing the split requires choosing the right exposure, not treating every China index as the same market.
Chinese equities split sharply during the first half of 2026. In a 2 June market snapshot, J.P. Morgan Asset Management put MSCI China down 8.5% for the year while the onshore CSI 300 was up 5.5%. Hang Seng Tech was down more than 10% and trailed global shares by roughly 20 percentage points. Those returns should be read as a dated snapshot, but the exposure gap behind them remains the more durable story.
MSCI China is not a purely offshore index. It includes large- and mid-cap A-shares at 20% of their free-float-adjusted market capitalisation, alongside Hong Kong shares, red chips, P chips and foreign listings. Yet its largest weights remain offshore giants such as Tencent and Alibaba. A foreign investor holding one broad fund therefore gets some mainland exposure. But it can still sit heavily underweight the domestic hardware and industrial names driving parts of the AI trade.
That composition explains much of the split. Offshore benchmarks lean toward internet platforms, consumption, finance and property, where a subsidy war fierce enough to be labelled ‘involution’ has damaged margins. J.P. Morgan said technology earnings estimates had been cut 37% over the previous year. Onshore indices carry more semiconductor, server, power-equipment and industrial-automation exposure: the physical layer on which AI systems depend. The real question is which companies and listings receive the spending first.
Down the supply chain
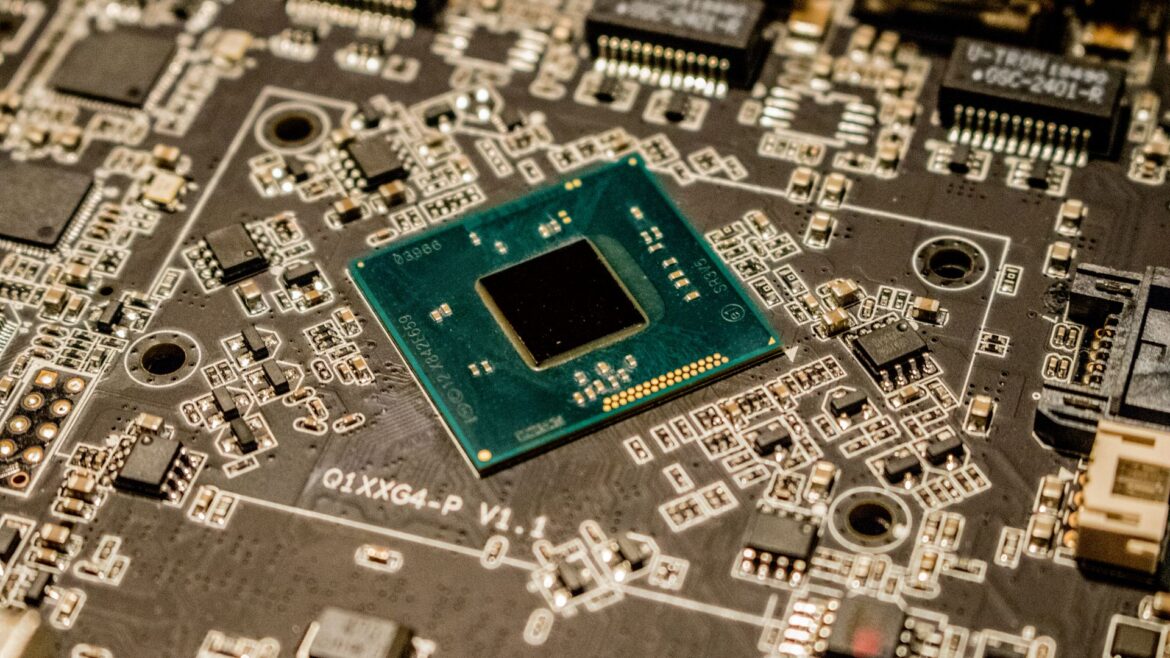
China’s integrated-circuit exports reached $177 billion in the first half of 2026, up more than 96% from a year earlier. Much of the increase reflected higher memory prices rather than a comparable jump in unit volumes, as suppliers allocated capacity toward the higher-value memory required by AI accelerators. April was the first month in the cited series when export value more than doubled year on year.
The average exported chip still fetched only about a dollar, a reminder that the category includes huge volumes of commodity components rather than only advanced processors. Some of the companies benefiting from higher prices or domestic substitution trade only in Shanghai or Shenzhen; others receive far larger weights in A-share benchmarks than in offshore-focused funds. Index investors can reach them, but only if they choose an exposure built to do so.
The robot question
Humanoid robots show both the opportunity and the danger of extrapolation. Morgan Stanley began 2026 expecting 14,000 Chinese shipments, raised the forecast to 28,000 in January and then to 50,000. The bank puts China’s humanoid market at about $2 billion in 2026 and $15 billion by 2030. Chinese manufacturers accounted for more than 80% of 2025 shipments, but the global industry shipped only about 13,000 units that year. Commercial use is arriving faster than expected; mass adoption and durable margins remain unproved.
The platform trap
Model developers offer a different kind of exposure. At a 29 May peak, Zhipu had risen about 1,600% from its January listing and reached a $112 billion valuation, despite 2025 revenue of 724 million yuan and an adjusted net loss of 3.2 billion yuan. MiniMax rose 109% on its debut. Dating those figures matters: a peak valuation is evidence of investor enthusiasm, not a permanent market value.
The operating losses make that enthusiasm harder to defend. On their latest reported 2025 figures, Zhipu lost roughly $12 for every dollar of revenue and MiniMax about $10. Both must compete with better-funded US model companies and with Chinese incumbents that already control cloud infrastructure, distribution and enterprise relationships. The younger firms may become important platforms, but their current valuations assume a great deal of that outcome in advance.
Selective, and liquid
The investable lesson is narrower than ‘buy China AI.’ Onshore benchmarks, offshore technology indices and broad China funds hold materially different portfolios. Semiconductor equipment, power systems and automation can rise while consumer platforms or property-linked shares fall. That rewards investors who understand the holdings beneath an index label, and it raises the cost of using one benchmark as a proxy for an entire economy.
For long-term investors who hold eligible listed Chinese securities, equity-backed financing can provide liquidity without requiring an immediate sale of the position. A qualified holder might use the cash to rebalance, meet another commitment or add selectively elsewhere while keeping economic exposure to the portfolio backing it. The facility does not solve the selection problem. A decline in the collateral can change its terms. It simply gives the investor another source of liquidity.
Reading the split
China’s popular indices are blunt instruments. MSCI China, Hang Seng Tech and the CSI 300 capture different listings, sectors and policy sensitivities. Investors who treat them as substitutes may miss the hardware, power-equipment and automation layers receiving the earliest AI spending, or mistake a rally in a few mainland themes for a broad national rebound. A single index is a poor map of an economy remaking itself in parts.